Buying a car with no money down sounds appealing—no large upfront payment, quicker approval, and instant access to the vehicle you need. But qualifying for a no-down-payment auto loan depends on one critical factor: your credit score.
Most lenders rely heavily on credit scores to assess borrower risk. Your score determines whether you qualify, how much you can borrow, and what interest rate you'll pay. If you’re applying for a loan without offering any down payment, the lender's risk increases. As a result, they look for borrowers with a strong credit profile.
This guide explains exactly what credit score you need to buy a car with no money down, what else lenders review during the approval process, and how to improve your chances of securing a favorable deal. You’ll also learn the potential risks and benefits of zero-down loans and what to do if your credit needs work.
II. How Credit Scores Affect Auto Loans
A credit score is a three-digit number that summarizes your credit risk based on your history of borrowing and repayment. Most auto lenders use the FICO Auto Score, a version of your credit score specifically tailored for auto financing.
The FICO Auto Score ranges from 250 to 900, compared to the traditional FICO Score range of 300 to 850. Lenders use this score to evaluate how likely you are to repay your auto loan on time.
Your score affects:
Loan approval: Higher scores mean better chances of getting approved.
Interest rates: Higher credit scores qualify for lower interest rates.
Loan amount: Better scores may allow larger loan amounts with no down payment.
Loan terms: Lower scores often mean shorter repayment periods or higher monthly payments.
Most lenders break credit scores into the following categories:
Credit Score Range
Category
Impact on Auto Loans
800–850
Excellent
Best rates, easiest approval, no down payment likely
740–799
Very Good
Very likely approval, low interest rates
670–739
Good
Likely approval, moderate interest rates
580–669
Fair
Possible approval with higher rates
Below 580
Poor
Difficult to qualify, large down payment required
A higher score doesn’t just improve your approval chances—it saves you money. According to Experian’s 2023 Auto Loan Report, borrowers with excellent credit (781–850) paid an average new car loan rate of 5.18%, while those with subprime credit (501–600) paid 14.08%.
III. What Credit Score Do You Need to Buy a Car with No Down Payment?
To qualify for a zero-down auto loan, lenders usually expect a minimum credit score of 660 or higher. This range falls within the “good” category and indicates a reliable borrowing history. However, requirements can vary by lender, loan type (new vs. used), and vehicle cost.
Here’s a breakdown:
Excellent Credit (740+)
Almost all lenders will offer no-down-payment loans.
You’ll receive the lowest available interest rates.
You may qualify for additional benefits, such as 0% APR promotions.
Good Credit (670–739)
Many lenders will still approve a zero-down loan, especially for new cars.
You may pay a slightly higher interest rate than prime borrowers.
Loan terms are usually favorable, but stricter underwriting may apply.
Fair Credit (580–669)
Approval is possible but more difficult.
Most lenders will require a down payment, though some subprime lenders may offer zero down.
Expect higher interest rates, possibly 10% or more.
Terms may include shorter loan periods and higher monthly payments.
Poor Credit (Below 580)
Very unlikely to qualify for no-money-down financing.
Lenders will usually require a large down payment (10–20% or more).
Interest rates can exceed 15%–20%.
Loan approvals often depend on additional factors like income, co-signers, or trade-ins.
No Credit History
If you have no credit, it’s very difficult to secure a loan with no down payment.
You’ll likely need a co-signer or proof of steady income and savings.
Some lenders offer first-time buyer programs, but these typically require a down payment.
Key takeaway: To get a car with no down payment, aim for a credit score of 660 or higher. If you’re under that threshold, other factors must be strong to get approved.
IV. Subprime Auto Loans and No Down Payment
If your credit score falls below 660, you’re likely in the subprime or deep subprime category. While getting a car loan with no money down in this range is more difficult, it is not impossible—especially with subprime lenders that specialize in higher-risk borrowers.
What Is a Subprime Auto Loan?
A subprime auto loan is a loan offered to individuals with limited or poor credit histories. These loans typically:
Carry higher interest rates (often between 10%–20% or more).
Include shorter terms or larger monthly payments.
May require more documentation, such as proof of income, residence, and references.
Some subprime lenders will advertise zero-down offers, but these deals often come with trade-offs:
You may be limited to certain vehicle types or older used cars.
Monthly payments may be significantly higher due to inflated interest rates.
You may be required to purchase additional insurance or vehicle protection packages.
You could be asked for a co-signer or agree to GPS tracking or starter interrupt devices as a condition of approval.
Who Offers Subprime Loans with Zero Down?
While most traditional banks avoid no-down-payment loans for subprime borrowers, certain dealership finance programs and online lenders may be more flexible.
Examples include:
Buy Here Pay Here (BHPH) dealerships: These finance in-house, often requiring no credit check. However, they charge extremely high interest and often inflate vehicle prices.
Captive finance companies: These are associated with automakers (e.g., GM Financial, Ford Credit) and may offer first-time buyer incentives or special finance options.
Online lenders: Companies like Capital One Auto Finance or Carvana may provide soft pre-approvals to subprime borrowers.
Important: Subprime loans with zero down may solve an immediate transportation need, but they come at a cost. The interest burden over time can lead to negative equity—owing more than the car is worth.
V. Factors Lenders Consider Besides Credit Score
Your credit score is important, but lenders also review several other financial indicators when you apply for a car loan. These help lenders assess your ability to repay the loan, especially when you're not providing a down payment.
1. Employment and Income Stability
Lenders want to see consistent employment and income. You may need to provide:
Pay stubs for the last 30–60 days
Tax returns or W-2s (for self-employed individuals)
Bank statements
Proof of employment tenure (2+ years preferred)
A stable job and steady income can sometimes offset a lower credit score, particularly if you're asking for zero down.
2. Debt-to-Income (DTI) Ratio
Your DTI ratio is the percentage of your monthly income that goes toward existing debts. Most lenders prefer a DTI below 40%–45%, including the potential car loan.
For example:
Monthly income: $4,000
Monthly debts (credit cards, loans, rent): $1,200
Proposed auto loan payment: $400
Total DTI: $1,600 ÷ $4,000 = 40%
If your DTI is too high, the lender may decline your application or require a down payment to reduce the loan amount.
3. Loan-to-Value (LTV) Ratio
The LTV ratio compares the loan amount to the vehicle’s value. If you want to finance the entire vehicle cost without a down payment, your LTV is 100%. This increases lender risk.
Lenders prefer LTV ratios closer to 80%–90%, which is why down payments are usually required.
4. Past Auto Loan History
If you've had a car loan before and made timely payments, this strengthens your application. A clean auto loan history signals to lenders that you can handle similar financial commitments.
5. Co-Signers and Trade-Ins
If your credit or income isn’t strong enough, a co-signer with better credit may help you qualify for zero down. Likewise, a trade-in vehicle with equity can act as a substitute for a down payment.
VI. Pros and Cons of No-Down-Payment Car Loans
Zero-down car loans offer convenience, but they come with trade-offs. It’s important to understand the benefits and risks before signing a no-money-down deal.
✅ Pros
Immediate access: You can get the car you need without waiting to save a lump sum.
Cash flow flexibility: Keep your cash for emergencies, bills, or other priorities.
Faster approval: With strong credit, approval is often quick and simple.
❌ Cons
Larger loan balance: Without a down payment, you finance the entire cost of the vehicle—plus taxes, fees, and interest.
Higher monthly payments: A bigger loan leads to higher monthly obligations.
Greater interest paid over time: Especially for borrowers with subprime credit, total interest can significantly exceed the car’s value.
Negative equity risk: You owe more than the car is worth (common in the first 2–3 years).
Stricter credit requirements: Fewer lenders offer zero down unless your credit is strong.
Key takeaway: A zero-down auto loan works best when you have good-to-excellent credit, stable income, and plan to keep the vehicle long-term.
VII. How to Improve Your Credit Score Before Applying
If your credit score is below 660 and you want to qualify for a no-down-payment auto loan, the best step you can take is to improve your credit score. Even a small increase can dramatically improve your approval odds and reduce your interest rate.
Below are five proven and compliant ways to improve your credit score before applying for a car loan:
1. Pay Down Credit Card Balances
Your credit utilization ratio—the percentage of your available credit that you’re using—affects up to 30% of your credit score. Lenders prefer utilization under 30%, and the lower, the better.
Example: If you have a $5,000 credit limit and your balance is $4,500, your utilization is 90%, which can lower your score. Paying this down to under $1,500 (30%) may boost your score within a few weeks.
2. Dispute Inaccurate Items on Your Credit Report
According to the Fair Credit Reporting Act (FCRA), you have the legal right to dispute inaccurate, outdated, or unverifiable items on your credit report. Common errors include:
File a dispute directly with the credit bureau(s) reporting the mistake
Bureaus must investigate within 30 days and either verify or remove the item.
3. Make All Payments on Time
Your payment history accounts for 35% of your FICO score. Making on-time payments consistently has the biggest long-term impact on your credit health.
Set up payment reminders or auto-pay to ensure you never miss a due date. Even one late payment can lower your score and make you ineligible for no-down-payment offers.
4. Avoid New Hard Inquiries
Each time you apply for credit, a hard inquiry appears on your credit report. Too many hard inquiries in a short period can lower your score and raise concerns about financial instability.
If you’re planning to apply for an auto loan, avoid applying for credit cards, personal loans, or store financing in the months leading up to your loan application.
5. Add Positive Tradelines Using Rent Reporting
If you’re a renter, consider using rent-reporting services like Rental Kharma. These services report your on-time rent payments to credit bureaus, adding a positive tradeline to your report.
This can:
Build your credit without taking on debt
Strengthen your payment history
Help increase your score if you have a thin credit file
Note: Rental Kharma does not remove negative items but helps add positive data.
Improving your credit score takes time and consistency. Most borrowers can raise their score by 30–100 points within 3 to 6 months by following these practices.
VIII. Conclusion
Getting a car loan with no down payment can save you from an upfront cost—but it requires strong credit and a stable financial profile. Most lenders look for a credit score of 660 or higher to approve zero-down financing. If your score is lower, approval is still possible, but interest rates will be higher, and additional conditions may apply.
Remember, lenders don’t only check your credit score. They evaluate your entire profile—income, employment history, debt ratios, and past loan performance. By understanding these factors, you can better prepare and increase your chances of securing favorable loan terms.
If your credit needs work before applying, it’s smart to start improving it now. Whether you're dealing with outdated collections, late payments, or reporting errors, you don’t have to face the credit repair process alone.
🛠 Let Credit Repair of Florida Help You Move Forward
Credit Repair of Florida provides legal, compliant, and results-driven credit repair services. We help clients:
Dispute inaccurate items
Understand their credit report
Rebuild credit over time
Prepare for major purchases like auto loans
With decades of experience and a client-first approach, our team helps you get back on track—so you can qualify for that no-down-payment car loan with confidence.
IX. FAQs
1. Can I get a car loan with no money down and bad credit?
It’s possible but difficult. Some subprime lenders may offer zero-down deals to borrowers with credit below 660, but these often come with very high interest rates, limited vehicle selection, and strict terms. In most cases, a down payment is required for subprime borrowers.
2. Is a 700 credit score good enough to get a car with no down payment?
Yes. A 700 credit score falls within the good credit range, and many lenders will approve a no-down-payment loan at that level. You’ll likely qualify for competitive interest rates and favorable loan terms.
3. Will a no-down-payment car loan hurt my credit score?
Not directly. However, taking out any new loan adds a hard inquiry and increases your debt-to-income ratio, which can temporarily impact your score. Over time, making on-time payments can help improve your credit.
If you’re preparing to apply for an apartment, you’re probably watching your credit score. But what landlords see on your credit report goes far beyond that single number. Landlords order your full credit report to look at patterns — how you handle debt, whether you’ve had collections or evictions, and what your financial behavior looks like month to month. Understanding exactly what they’re reading gives you the ability to prepare, explain, and improve before you apply.
Last updated: August 2026 | Estimated reading time: 8 minutes
Quick Answer
Landlords typically look at your full credit report — not just your score. The sections they pay the most attention to are payment history, collections (especially rental collections), public records like bankruptcies, and your overall pattern of managing debt. Most landlords use tenant screening services like TransUnion SmartMove or RentSpree to access this report. Two applicants with the same score can get very different results depending on what their reports actually contain.
Key Takeaways
Landlords order your full credit report, not just your score — every section matters.
Payment history and collections are the most scrutinized sections, especially rental-related collections.
Evictions do not appear directly on credit reports, but unpaid rent sent to collections does — and that’s just as damaging.
You can review your own report free at AnnualCreditReport.com and dispute errors before a landlord sees them.
Proactively reporting rent payments through a service like Rental Kharma can add positive tradelines that landlords and lenders see.
Your credit score is a single number calculated from your full credit history. Two renters can both have a 650 score — but one might have a recent eviction or a string of late payments, while the other has a clean record with one old issue. Landlords know this, which is why they look at the full report, not just the number.
Most landlords use tenant screening services — TransUnion SmartMove, RentSpree, Experian RentBureau, or similar platforms — to pull a combined report that includes credit history, eviction records, and sometimes criminal background. What they’re looking for is a pattern: does this person pay their obligations consistently, or do they have a history of ignoring debt?
What Landlords Are Really Evaluating
Beyond the individual data points, landlords are asking: Can this applicant reliably cover rent every month? Do they have a history of disappearing on debts? Have they been evicted or had rental collections before? Is there anything that suggests a pattern of financial instability? The answers are in the full report — and that’s exactly what they’re reading.
What Landlords See on Your Credit Report — Section by Section
Payment History
Payment history is the most heavily scrutinized section. Landlords look at whether you pay on time, how often you’re late, how recently late payments occurred, and whether the late payments involve rent or utility bills specifically. A pattern of on-time payments over the past two to three years carries significant weight. Older late payments from three or more years ago — especially if followed by a clean record — are often viewed more leniently.
One or two late payments in recent months, however, can be enough to raise a red flag — particularly on a rental or utility account, which directly predicts rent payment behavior.
Collections and Charge-Offs
Collections are among the most damaging items a landlord can see. A collection account means a creditor gave up on the debt and sent it to a collections agency, which is then reported to the bureaus. Rental collections — unpaid rent or utilities that went to a collector — are the most disqualifying items possible on a rental application. They tell a landlord exactly what they’re most afraid of: that a previous landlord couldn’t get paid.
Non-rental collections, like medical debt, may be viewed more leniently depending on the amount and age. Understanding how collection tradelines appear on your report can help you identify what a landlord is seeing and how to address it before you apply.
Public Records
Bankruptcies appear on credit reports and are visible to landlords. A Chapter 7 bankruptcy stays on your report for up to ten years; a Chapter 13 stays for seven. A recent bankruptcy — within the past two years — is likely to disqualify you from most professionally managed properties, though private landlords may be more flexible. Civil judgments rarely appear on credit reports anymore following 2017 bureau changes, but they can surface in public record searches during tenant screening.
Credit Inquiries
Hard inquiries — the kind that appear when someone pulls your credit to evaluate a credit application — are visible to landlords. One or two inquiries are normal and unlikely to raise concerns. Excessive inquiries — five or more in a short period — can signal that an applicant is being turned down repeatedly or is aggressively seeking new credit, both of which may concern a landlord.
Open Accounts and Credit Utilization
Landlords also look at how you manage existing credit — whether accounts are in good standing, whether balances are high relative to limits, and whether you have a stable, long-standing credit history. High credit utilization — carrying balances close to your credit card limits — signals financial stress even when no payments are late.
Rental History on Your Credit Report
Traditional credit reports do not automatically include rent payment history — most landlords don’t report to the bureaus. However, if you have used a rent reporting service like Rental Kharma, your on-time rental payments can appear as a positive tradeline on your TransUnion and Equifax reports. Conversely, unpaid rent that was sent to a collections agency will appear as a collections account — even though evictions themselves don’t appear directly on credit reports.
How to Clean Up Your Report Before Applying
Pull Your Reports First
Before applying to any rental, pull your own credit reports from all three bureaus at AnnualCreditReport.com — you can access them free weekly. Read through every section the way a landlord would. Identify anything that could raise a concern — late payments, collections, high balances — and decide whether it can be addressed before you apply.
Dispute Inaccurate Information
Errors are common on credit reports — accounts that don’t belong to you, duplicate entries, wrong payment statuses, or outdated collection accounts that should have aged off. You have the right under the Fair Credit Reporting Act (FCRA) to dispute any item that is inaccurate, incomplete, or unverifiable. The bureau has 30 days to investigate. If the information can’t be verified, it must be removed. Disputing errors before a landlord sees them can meaningfully change what the report shows.
Pay Down Outstanding Balances
High credit card balances raise your utilization ratio, which landlords see as financial stress. If you can pay down balances before applying — especially on any card close to its limit — do it. Even bringing one card from 90% utilization to 50% can make a visible difference in how your report reads.
Bring Past-Due Accounts Current
If you have accounts that are currently delinquent, bringing them current before applying is worth doing even if you can’t pay off the full balance. “Paying as agreed” on recent accounts shows a landlord you are actively managing your obligations — a much more favorable signal than continuing to fall behind.
Building Positive Rental History on Your Report
Most rent payments are invisible on credit reports — landlords simply don’t report them. But that doesn’t mean you’re powerless. Rent reporting services allow you to proactively add your on-time rental payment history to your credit file, creating a positive tradeline that both landlords and lenders can see.
Rental Kharma is one of the longest-running services of this kind. It reports your rent payments to TransUnion and Equifax — and can report retroactively, meaning years of on-time rent you’ve already paid can be added to your report at enrollment. As of 2026, it costs approximately $8.95/month plus a one-time setup fee. Your landlord doesn’t need to sign up for any platform — Rental Kharma simply contacts them to verify your payment history.
This is particularly useful if you have a thin credit file or a history of credit issues you’re working to overcome. A long record of consistent on-time rent payments is exactly the kind of positive data that can offset older negative items in a landlord’s eyes.
Want to know exactly what a landlord would see on your report right now?
We review your full credit report across all three bureaus and walk you through every item — what it means, how a landlord would read it, and what you can do about it. Free, no obligation.
We do not guarantee deletions, approvals, or a specific score increase — no legitimate company can.
What landlords see on your credit report is your full credit history — not just your score. This includes your payment history (on-time and late payments), collection accounts, public records like bankruptcies, credit inquiries, open and closed accounts, credit utilization, and any positive tradelines from rent reporting services. Rental collections and recent late payments are the sections they scrutinize most closely.
How far back do landlords look at credit history?
Landlords review your full credit history, but pay closest attention to the last two to three years. Recent patterns — good or bad — carry significantly more weight than older issues. A late payment from five years ago with a clean record since then is viewed very differently from a late payment from six months ago.
Do landlords care more about credit score or income?
Both matter, and a strong showing in one can offset a weaker one in the other. Most landlords want to see a score of at least 620 to 650 and gross monthly income of 2.5 to 3 times the monthly rent. A high income with a lower score is often more workable than a high score with insufficient income — landlords are ultimately most concerned about whether rent will be paid.
Challenging Situations
Can I still rent with an eviction on my credit report?
Evictions don’t appear directly on credit reports — they show up in separate eviction databases that tenant screening services check. However, unpaid rent that went to collections does appear on your credit report and is treated as a major red flag. Some private landlords are more flexible than large property management companies. Being upfront about the situation, providing strong references from previous landlords, and offering a larger security deposit can all help.
What can I do if my credit report has errors before a rental application?
Pull your free credit reports from AnnualCreditReport.com and review all three bureaus. If you find inaccurate, incomplete, or unverifiable items — wrong payment statuses, accounts that aren’t yours, outdated collections — file a dispute with the bureau reporting the item. The bureau has 30 days to investigate. Correct any errors before you apply, because a landlord’s decision may be made before you have time to fix something after the fact.
Renting a new apartment? Your credit score might matter more than you think. So what’s the average credit score to rent an apartment, and how close do you need to get to it? Whether you’re applying for a luxury high-rise or a modest studio, most landlords check your credit as part of tenant screening to gauge whether you’re likely to pay rent on time. In a competitive rental market, your score can be the deciding factor between approval and a denial.
This guide explains what score landlords typically expect, what else they look at beyond the number, and — new for 2026 — how paying rent on time can now actually help build your credit, not just get you approved for it.
Last updated: July 10, 2026
Estimated reading time: 10 minutes
Key Takeaways
There’s no single official minimum, but data suggests the average approved renter’s score falls somewhere in the high 600s.
Many landlords use 620–650 as an informal benchmark, with 700+ giving you a much stronger position.
Landlords weigh income, rental history, and background checks alongside your score — not the score alone.
A lower score doesn’t rule you out — a bigger deposit, a co-signer, or strong references can offset it.
As of late 2025, renters can now report their own on-time rent payments to build credit, not just spend it getting approved.
Your credit report and score are a financial snapshot built from your payment history, credit utilization, account types, and length of credit history. Landlords use it to gauge whether you’re likely to pay rent on time and in full. A higher score generally signals reliable past payment behavior; a low score may suggest missed payments, defaults, or past evictions.
A lower score doesn’t automatically mean rejection — it can just mean different terms:
A higher security deposit
A shorter lease term
A requirement for a co-signer or guarantor
Knowing where you stand — and how your score is actually calculated — before you apply lets you prepare rather than get caught off guard.
What Is the Average Credit Score to Rent an Apartment?
There’s no official nationwide minimum — every landlord sets their own bar. Recent data on this varies by source: some industry reports have put the average score among approved renters in the high 600s, while a more recent nationwide renter survey put the figure closer to the high 630s, with the minimum for low-end units around 597, mid-level around 626, and high-end closer to 669. The honest takeaway is that averages shift by report, city, and property type — treat any single number as a rough benchmark, not a hard cutoff.
Different types of housing come with different credit expectations. Luxury apartments in competitive markets usually require higher credit scores, often above 700, since property managers in these complexes want assurance that tenants can meet the financial demands of high-end living. Standard rentals or mid-tier apartments tend to accept renters with scores in the mid-600s, depending on the landlord’s individual risk tolerance. On the lower end, low-income housing and subsidized programs may approve applicants with scores below 600, especially when paired with proof of stable income or government support.
Geographic location plays a real role too. In urban markets where demand is high, landlords may set stricter credit thresholds simply because they can afford to be selective. Suburban or rural areas, with less competition for units, often offer more lenient requirements. Income level and overall market competitiveness feed into this as well — in cities where rent prices run high, applicants typically need stronger credit to demonstrate they can manage the financial commitment. While these averages provide helpful context, remember that each landlord ultimately sets their own criteria; knowing where you stand and coming prepared with supporting documentation matters more than chasing a specific number.
What Florida Renters Should Know
The average credit score to rent an apartment in Florida follows the same national patterns above, but Florida renters have a few state-specific protections worth understanding before signing a lease. Florida doesn’t cap security deposit amounts by state law — a landlord can generally set the deposit at whatever level they choose, which is part of why a larger deposit is such a common trade-off offered to applicants with lower credit scores. What Florida law does regulate is the timeline for returning it: under Florida Statute §83.49(3), a landlord who intends to keep some or all of a security deposit must notify the tenant in writing within 30 days of move-out, or risk forfeiting the right to claim it.
Florida also doesn’t have a statewide cap on rental application or screening fees, unlike some other states, so it’s reasonable to ask upfront what the fee covers and whether any portion is refundable if you’re not selected. None of this changes how your credit score is evaluated, but knowing your rights around deposits and fees puts you in a stronger position going into any Florida rental application — regardless of what your score looks like.
What Score Is Considered “Good Enough”?
Most landlords reference the FICO scoring categories, even if informally, to decide how to treat an application:
300–579: Poor. A history of missed payments or defaults. Approval is very difficult.
580–669: Fair. Still considered risky — may require a higher deposit or co-signer.
670–739: Good. Responsible credit use. Many landlords approve tenants in this range.
740–799: Very Good. Strong habits, low missed-payment risk. Usually qualifies easily.
800+: Excellent. Often leads to faster approvals and better terms.
Landlords don’t always follow these categories strictly. In practice, many treat 620–650 as an informal minimum benchmark for approving an application. If your score falls below that line, you may still get approved, but likely with conditions attached — a larger security deposit, a shorter lease term, or a co-signer requirement. A credit score of 700 or above puts you in a noticeably stronger position in competitive rental markets: it shows landlords not just that you’re able to pay your bills, but that you consistently do so on time, which often translates into smoother approvals, better lease terms, and lower upfront costs. Check what counts as a good credit score for more context on where you currently stand — and if you’re not quite where you want to be, there are concrete steps you can take before applying.
What Landlords Actually Look At Beyond the Score
Your score is one input, not the whole decision. Most landlords and property managers don’t rely on the number alone — they review your full credit report and supporting documents, which means even a slightly below-average score doesn’t automatically disqualify you if the rest of your profile is strong.
Payment history
Landlords typically conduct a full credit report review, checking whether you’ve consistently paid bills on time. Missed payments, delinquencies, and charge-offs raise concerns even if your score clears their threshold. A pattern of responsible use builds trust. Negative marks suggest risk regardless of the headline number.
Income verification
Landlords also verify income to determine whether you can comfortably afford the rent. A common standard is the rent-to-income ratio, where monthly rent shouldn’t exceed roughly 30–35% of your gross income. If your income is too low relative to the rent, a landlord may decline your application even with good credit — but on the flip side, a high income can sometimes compensate for a lower score.
Rental history
Landlords may request references from past landlords or review your tenancy history directly. Consistently paying rent on time, following lease terms, and maintaining good relationships with previous landlords works in your favor. If you have no rental history at all, expect a request for a co-signer or additional proof of financial stability.
Background checks
Most landlords run a background check covering eviction history, criminal records, and other public records. An eviction on your record — especially a recent one — can significantly hurt your chances even with a solid score. Unresolved legal issues or negative reports can raise similar concerns.
Understanding that landlords look beyond the average credit score to rent an apartment means you can prepare more strategically: strengthening your income documentation, keeping records clean, and lining up positive references can meaningfully balance out less-than-perfect credit.
What to Do if Your Score Is Below Average
A below-average score doesn’t have to end your search. Many renters with lower scores successfully secure housing by preparing well and using alternative ways to demonstrate reliability. The goal is showing a landlord you can be trusted to pay on time and care for the property, even if your credit history isn’t ideal.
Offer a higher security deposit
This gives the landlord added financial protection and reduces their perceived risk. It won’t change your credit score, but it does show you’re serious about the apartment and financially prepared to move in.
Use a co-signer or guarantor
A co-signer is someone with good credit who agrees to take legal responsibility for your lease if you fail to pay. Many landlords accept applications with co-signers, especially for renters with fair income but low credit scores — just make sure the co-signer fully understands what they’re agreeing to before you ask.
Gather references and proof of stable income
Letters from previous landlords confirming your rent was paid on time carry real weight, and recent pay stubs, bank statements, or employment verification reassure a landlord about your financial stability.
Consider private landlords
Individual landlords often have more flexible criteria than large property management companies and may be more willing to consider your whole situation, including a letter of explanation or alternative financial documentation.
Tips to Improve Your Credit Before Renting
Even a small score increase can change your terms — the difference between standard conditions and being asked for extra deposits or a co-signer. A few proven, time-tested strategies:
Pay down credit card balances
Your credit utilization ratio — how much of your available credit you’re using — makes up a large portion of your score. Keeping balances below 30% of your limit can meaningfully boost your score, and reducing high balances is often the fastest lever you have before submitting a rental application.
Review your credit report for errors
Many consumers discover inaccurate or outdated information dragging their score down — accounts that aren’t theirs, incorrect payment statuses, or duplicate entries. Under the Fair Credit Reporting Act, you have the legal right to dispute inaccurate data directly with Equifax, Experian, and TransUnion and request a timely correction.
Make on-time payments the priority
Payment history is the single largest factor in your credit score. Paying credit cards, loans, and utility bills on time every month shows financial discipline, and if you’ve missed payments in the past, starting a new pattern today is noticed by both credit bureaus and landlords over time.
Avoid new hard inquiries close to your application
Every new credit application results in a hard inquiry that can temporarily lower your score and signal financial instability to a landlord reviewing your file. If you know you’ll be applying for a rental soon, pause unnecessary credit activity to keep your score steady — and if you suspect an inquiry on your report wasn’t authorized in the first place, here’s how to remove unauthorized credit inquiries the legal way.
New: You Can Now Build Credit by Paying Rent
This is a genuinely new development for renters. Historically, on-time rent payments never showed up on your credit report at all — they simply weren’t counted, even though rent is often a renter’s single largest monthly expense. That’s changing quickly.
According to a TransUnion report released in September 2025, 13% of consumers had rent payments reported to credit bureaus in 2025, up from 11% in 2024. That trend got a significant boost in July 2025, when the Federal Housing Finance Agency (FHFA) ordered Fannie Mae and Freddie Mac to begin accepting VantageScore 4.0 for mortgage underwriting — a scoring model that can factor in rent payment history, giving renters a more direct path from paying rent to eventually qualifying for a mortgage.
In November 2025, Zillow launched CreditClimb, powered by the rent-reporting company Esusu, which lets any renter nationwide report their on-time rent payments to all three major credit bureaus for about $20 a year — and even backdate up to two years of past payments. It’s not the only rent-reporting option available, but it’s a sign of how mainstream this has become.
The practical takeaway: if you’re currently renting and paying on time, it may be worth checking whether your landlord already reports payments, or looking into a self-reporting service, before you assume your credit history can’t improve until you have new lines of credit. Rent might already be working in your favor — it just isn’t being counted yet.
Beat the Average Credit Score to Rent an Apartment
If credit issues are holding your rental search back, Credit Repair of Florida can help you review your credit report and understand what’s actually affecting the average credit score to rent an apartment in your target market. We do not guarantee deletions or a specific score increase — no legitimate company can — but we can help you approach your next application with a clear, realistic plan.
Yes. You’ll likely need alternative proof of financial responsibility — recent pay stubs, bank statements, or an employer letter. Some landlords may also ask for a co-signer or larger deposit.
Will checking my credit to rent hurt my score?
No. Rental credit checks are usually soft inquiries, which don’t affect your score. Only hard inquiries — like applying for a credit card or loan — can cause a temporary dip.
Can I rent with bad credit if I have a co-signer?
Often, yes. A co-signer agrees to take financial responsibility if you default on rent, which gives many landlords enough assurance to approve an applicant with low credit or limited history.
Do all landlords require a credit check?
No. Private landlords are often more flexible and may rely on income verification or personal references instead of comparing you to the average credit score to rent an apartment. Larger property management companies are more likely to run a standard credit check.
Improving and Building Credit
How long does it take to improve my credit score?
It depends. Small changes like paying down balances can help within weeks. Bigger improvements, like building a longer on-time payment history, typically take three to six months or more.
Can paying my rent on time actually raise my credit score now?
It can, if the payments are actually being reported. Rent isn’t automatically included in your credit file. Some landlords report it directly, and services like Zillow’s CreditClimb let renters self-report on-time payments to all three bureaus for a small annual fee.
Does a denied rental application show up on my credit report?
No. A rental credit check itself is typically a soft inquiry and won’t appear as a negative mark. A denial isn’t reported to credit bureaus — it’s a decision made by the landlord, not an entry on your file.
This article is provided for general educational purposes and is not legal, tax, or financial advice. Rent-reporting services, fees, and program details may change — verify current terms directly with the provider before enrolling.
When you review your credit report, you’ll usually find a list of inquiries — records of who has checked your credit and when. One of the most common questions we hear is how to remove unauthorized credit inquiries. The honest answer depends entirely on whether the inquiry was actually authorized. This guide explains exactly what you can legally do, using your rights under the Fair Credit Reporting Act (FCRA).
Last updated: July 3, 2026
Estimated reading time: 9 minutes
Key Takeaways
You cannot remove a legitimate hard inquiry that resulted from your own credit application.
You can dispute and remove inquiries you didn’t authorize, or that are inaccurate.
Hard inquiries typically stay on your report for 2 years but affect your score for around 12 months.
Soft inquiries never affect your score and aren’t visible to lenders.
Both Experian and Equifax have faced CFPB enforcement action for mishandling consumer disputes — always confirm your dispute actually resolved, don’t assume it did.
A credit inquiry is a record of when someone checks your credit report. Lenders, credit card companies, landlords, and employers can all trigger one, depending on the situation. Inquiries fall into two categories, and the distinction matters a lot.
Hard inquiries
A hard inquiry happens when a lender reviews your report to make a lending decision — applying for a mortgage, a credit card, or auto financing all trigger one. Each hard inquiry can reduce your score by roughly 2 to 5 points, and several in a short window can make lenders view you as higher risk. Hard inquiries stay on your report for two years, though their effect on your score typically fades after about 12 months.
Soft inquiries
A soft inquiry happens when you check your own credit, or when a company checks it without making a lending decision — background checks and pre-approved offers fall here. Soft inquiries never affect your score and aren’t visible to lenders.
How to remove unauthorized credit inquiries: authorized vs. unauthorized
Review your report regularly to confirm every inquiry was actually authorized. An unauthorized hard inquiry can result from identity theft or a clerical error on the lender’s end. Learning to remove unauthorized credit inquiries starts with correctly identifying them — this is a legitimate, important part of protecting your credit, not a shortcut or a loophole.
What actually triggers a hard inquiry
Beyond the obvious examples, hard inquiries can come from more places than people expect:
Mortgage, auto loan, or personal loan applications
New credit card applications, including store cards
Some apartment rental applications, depending on the landlord’s screening process
Certain cell phone or utility account setups, if the provider checks credit to determine a deposit
Private student loans (federal student loans generally don’t trigger a hard inquiry)
Rate shopping doesn’t have to cost you as much as you’d think
One detail people often miss: credit scoring models build in a “deduplication” window for rate shopping on mortgages, auto loans, and student loans. If you apply with multiple lenders for the same type of loan within a focused window — typically 14 to 45 days depending on the scoring model — those inquiries are usually counted as a single inquiry for scoring purposes, not several. The practical takeaway: if you’re shopping rates, do it in a tight window rather than spreading applications out over months. This applies to loan shopping specifically; it doesn’t apply to credit card applications, which are each counted separately.
Your Rights Under the FCRA
The Fair Credit Reporting Act gives you the right to dispute any inaccurate or unauthorized item on your report, including hard inquiries. The three major bureaus — Equifax, Experian, and TransUnion — must keep the data they report accurate, fair, and current.
A lender must have a “permissible purpose” to pull your report. Without your authorization or a legitimate reason, the inquiry is invalid, and you can dispute it. You can also request the name and contact information of whoever pulled your report, and demand evidence of your authorization.
Always review reports from all three bureaus — an inquiry may appear on one and not the others, since not every lender reports to all three.
Step-by-Step: How to Remove Unauthorized Credit Inquiries
Step 1 — Get your reports. Visit AnnualCreditReport.com, the only federally authorized source, and review each bureau’s report line by line.
Step 2 — Identify unfamiliar inquiries. Flag anything you don’t recognize, and cross-check against your own applications, emails, and account history.
Step 3 — Draft a specific dispute. Include your information, the exact inquiry in question, a statement that you didn’t authorize it, and a request for investigation. Send it via certified mail and keep a copy. The FTC’s guide to disputing credit report errors includes a sample letter format you can adapt.
Step 4 — Use each bureau’s dispute process. This is how you actually remove unauthorized credit inquiries in practice: Equifax, Experian, and TransUnion each offer online dispute portals — the CFPB’s guide below links directly to all three, and your credit report itself will list the current dispute contact for that bureau.
Step 5 — Request permissible-purpose proof. Ask the creditor to provide written proof of your authorization. If they can’t, that strengthens your dispute.
Step 6 — Escalate if needed. Bureaus generally have 30 days to investigate. If they don’t respond or remove the inquiry, file a complaint with the CFPB or consult a consumer protection attorney.
Worth knowing: Between 2024 and 2025, the CFPB took enforcement action against both Experian and Equifax for failing to properly investigate consumer disputes — Equifax was fined $15 million. That doesn’t mean disputes don’t work, but it’s a good reason not to assume a dispute was resolved just because the deadline passed. Check the actual updated report yourself.
What Not to Do When Disputing Inquiries
Don’t dispute legitimate inquiries. You cannot legally remove a valid hard inquiry that resulted from your own application, no matter how much you’d like to.
Avoid generic templates. Mass-produced dispute letters found online are often ignored by bureaus — use specific, factual letters tied to your actual situation.
Watch for scam services. Be skeptical of anyone promising instant or guaranteed removals — these often rely on unethical methods that can backfire.
Never file false disputes. Disputing an inquiry you actually authorized is against the law, can damage your credibility, and can carry legal consequences.
Don’t bother disputing inquiries that have already aged off. Hard inquiries drop off your report automatically after two years — check the date before spending time on a dispute that’s already moot.
Don’t ignore the bureau’s written response. A dispute “closed” isn’t the same as “resolved in your favor” — read the actual outcome and pull an updated report to confirm the change took effect.
Preventing Unnecessary Inquiries Going Forward
The best long-term strategy is limiting how many new hard inquiries you generate in the first place.
Apply only when you need to. Each new application is a potential hard inquiry — pause before applying for credit you don’t actually need right now.
Use credit monitoring. Tools that alert you to new inquiries help you catch unauthorized activity quickly, while it’s still easy to dispute.
Read the fine print on “pre-approved” offers. Pre-qualification checks are typically soft inquiries, but actually accepting and completing the application usually triggers a hard one.
Time major applications together. If you know you’ll need both a mortgage and a car loan, understanding the rate-shopping window above can help you plan the order and timing.
When to Work With a Credit Repair Professional
If your report has multiple unauthorized inquiries, professional help can save time — a credit repair expert can analyze your report, identify suspicious activity, and communicate with the bureaus on your behalf. If you’re weighing whether to hire one, our guide on how to compare credit repair companies in Florida walks through what to look for.
Make sure any company you consider is transparent and compliant with the federal Credit Repair Organizations Act (CROA). In practice, that means: it cannot charge or accept payment before it fully performs the agreed service, and if you sign a contract, Florida law gives you 5 days to cancel while federal CROA separately gives you 3 business days — our guide to Florida credit repair laws covers these protections in more detail. Walk away from anyone who asks for large upfront payments, promises results within 24–48 hours, or tells you to misrepresent facts — those are the same warning signs covered in our guide on how to avoid credit repair scams in Florida.
A good credit repair company educates you — it doesn’t just promise removals.
Talk to a Team That Explains, Not Just Promises
Credit Repair of Florida can help you review your credit report and take the right steps to remove unauthorized credit inquiries or dispute other items worth challenging. We do not guarantee removals or a specific score increase — no legitimate company can.
No. Only unauthorized or inaccurate hard inquiries can be removed. Legitimate inquiries from your own applications stay on your report, and soft inquiries aren’t visible to lenders in the first place.
How long does it take to remove an inquiry?
Once you file a dispute, bureaus generally have 30 days to investigate and respond.
Will removing an inquiry increase my score?
Possibly, but the increase is usually small. Removing unauthorized entries mainly protects the accuracy of your report, which matters on its own.
What if the creditor doesn’t respond to a dispute?
If the creditor can’t provide proof of your authorization, the bureau must remove the inquiry.
Can I file multiple disputes at once?
Yes — just make sure each dispute is accurate, specific, and backed by evidence rather than a generic mass template.
Does rate shopping for a mortgage or auto loan hurt my score more than one inquiry would?
Usually not. Scoring models typically count multiple inquiries for the same type of loan within a focused window — commonly 14 to 45 days — as a single inquiry. This deduplication doesn’t apply to credit cards, which are counted individually.
Can checking my own credit trigger a hard inquiry?
No. Checking your own credit is always a soft inquiry. It never affects your score and isn’t visible to lenders.
Is it worth disputing an inquiry that’s about to age off anyway?
Generally no. Hard inquiries fall off your report automatically after two years. Check the date before spending time on a dispute — if it’s about to expire on its own, your effort is better spent elsewhere.
This article is provided for general educational purposes and is not legal, tax, or financial advice. Laws and requirements may change, and their application depends on the facts. Consult a qualified attorney for advice about a specific situation.
How long do tradelines stay on your credit? This is one of the most common — and most important — questions people ask when reviewing their credit reports. In simple terms, a tradeline is the record of an account on your credit report. Whether it’s a credit card, auto loan, student loan, or mortgage, every account you open gets reported to the bureaus as a tradeline.
Each tradeline tells a story — how long you’ve had the account, whether you’ve paid on time, how much you owe, and whether it’s open or closed. Understanding how long that story stays visible matters, because tradelines directly affect the biggest components of your credit score: payment history, utilization, and account age.
Last updated: August 27, 2026
Estimated reading time: 14 minutes
Key Takeaways
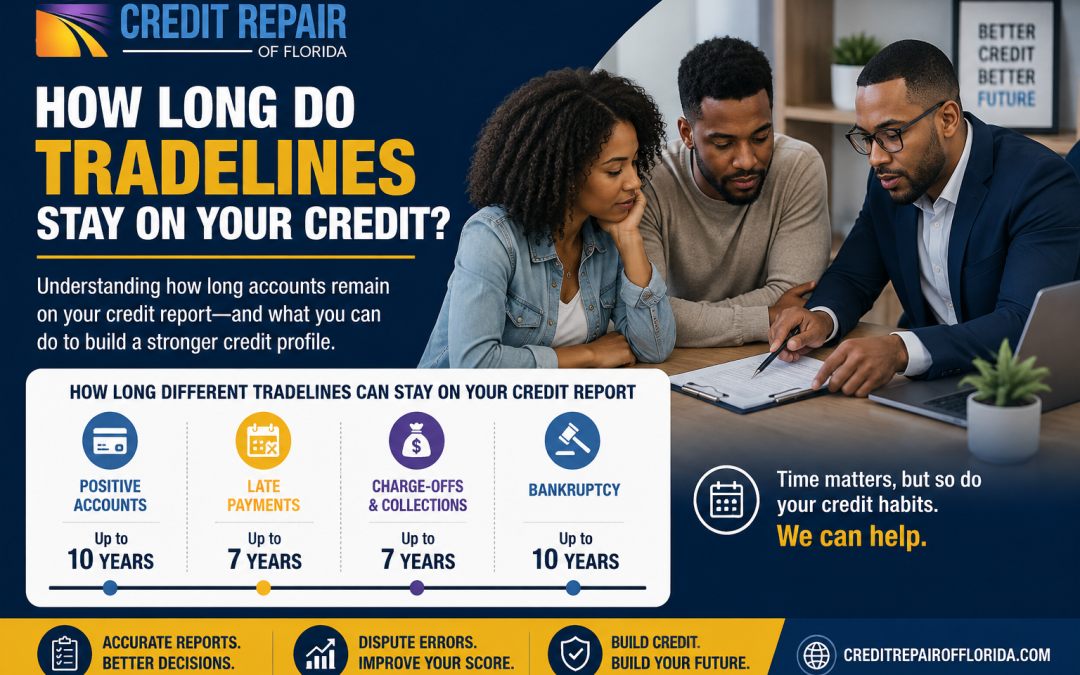
Open, active accounts in good standing stay on your report indefinitely as long as they’re reported.
Closed positive accounts typically stay up to 10 years from the closure date — and keep helping your score.
Negative tradelines (late payments, collections, charge-offs) generally fall off after 7 years from the original delinquency date.
Chapter 7 bankruptcy can stay up to 10 years; Chapter 13 typically 7 years.
These timelines are set by the FCRA — a legitimate dispute can only remove a tradeline early if it’s actually inaccurate or unverifiable.
When you open any credit account, a tradeline is automatically created on your credit report. This includes credit cards, auto loans, mortgages, personal loans, and student loans. Every account reported to a bureau by a bank, lender, or credit card company becomes a separate tradeline in your credit history.
Two types of tradelines
Revolving tradelines include credit cards and lines of credit — you borrow repeatedly up to a set limit and repay over time. Installment tradelines include fixed loans like mortgages, auto loans, and student loans — you borrow a lump sum and repay it in scheduled payments. Both affect your score differently: revolving tradelines influence your utilization ratio, while installment tradelines affect your debt-to-income balance and payment history.
What’s inside a tradeline
Every tradeline contains detailed information that scoring models use to evaluate your financial behavior: account type, open/close date, payment history, credit limit or loan amount, and current balance. Lenders typically update this information every billing cycle and send it to Equifax, Experian, and TransUnion. Even a single missed payment or a large balance increase can meaningfully shift your rating.
How Long Do Tradelines Stay on Your Credit Report?
Tradelines don’t all follow the same removal schedule. Their duration depends on whether the account is open, closed in good standing, or tied to negative activity.
Open tradelines
Active accounts in good standing remain on your report indefinitely, as long as the account stays open and the lender continues reporting.
Closed positive tradelines
Accounts paid in full with no issues usually stay on your report for up to 10 years from the date of closure. They keep helping your score the entire time.
Negative tradelines
Accounts with charge-offs, late payments, collections, or defaults generally remain on your report for 7 years from the original date of delinquency. This applies to most negative credit items. Medical debt reporting has its own recent changes worth understanding separately, since the rules there have shifted in ways that don’t apply to other debt types.
Bankruptcies
Not technically a tradeline, but commonly confused with one. Chapter 7 can stay on your report for up to 10 years, while Chapter 13 typically remains for 7 years.
These timeframes are set by the Fair Credit Reporting Act, which regulates how long credit bureaus can report financial information. Understanding them helps set realistic expectations. Old positive accounts may keep boosting your score long after you’ve stopped using them. Old negative marks may become disputable once their reporting window has genuinely expired.
Impact of Tradelines on Your Credit Score Over Time
Tradelines feed directly into scoring models like FICO and VantageScore, which assess several core metrics:
Payment history (35%). Lenders want to see consistent on-time payments — positive tradelines strengthen this category over time.
Amounts owed (30%). This includes your utilization ratio — high balances on revolving tradelines can pull your score down.
Length of credit history (15%). Older tradelines improve your score by showing long-term use — closed positive accounts still count here.
Credit mix (10%). A balance of revolving accounts and installment tradelines shows responsible use.
New credit (10%). Opening new tradelines affects your score temporarily due to hard inquiries, but can help over time if managed well.
In the short term, a new tradeline may cause a slight dip, especially if it includes a hard inquiry or new debt. Over time, though, consistent positive activity — like on-time payments — adds significant value. A credit card you’ve held for years and paid on time every month will help your score far more than a newly opened card in good standing.
Positive vs. negative tradelines: what to know
Positive tradelines — current accounts with a history of timely payments — act as credit builders throughout their entire life on your report, not just while you’re actively using them. A card you paid off and closed five years ago is still working in your favor today, quietly supporting your average account age and your payment history.
Negative tradelines work the opposite way. A single 30-day late payment, a collection account, or a charge-off can drop your score quickly, often more quickly than positive activity builds it back up. Then it sits on your report for years afterward. This asymmetry is exactly why prevention matters more than damage control: one missed payment can undo months of careful, positive account management. If you’re unsure whether a negative mark on your report is even accurate, understanding these timelines helps. It shows you the difference between an item that’s simply unwanted and one that’s genuinely worth disputing.
The Role of Installment Tradelines in Credit Repair
Installment tradelines — auto loans, personal loans, mortgages, student loans — provide predictability and structure that scoring models value. Maintaining these accounts with timely payments is one of the most effective ways to show creditworthiness. Consistent payments build positive history (35% of your score) and diversify your credit mix (up to 10%). Older paid-off loans keep contributing positively for years after they close.
Mismanaged installment tradelines carry real risk, though. Missed or late payments can quickly drop your score and trigger collection actions. A defaulted loan may appear as a negative tradeline for up to 7 years. Many people don’t realize that a successfully paid-off car loan, for instance, remains on the report for up to 10 years. It keeps demonstrating responsible behavior long after the loan itself is gone.
What Happens When Tradelines Are Removed?
Every tradeline eventually leaves your report, either through natural expiration or through a dispute. Natural expiration follows the timelines above — positive accounts around 10 years after closure, negative items around 7 years from the delinquency date.
Early removal happens through disputes. If a tradeline is inaccurate, outdated, or unverifiable, you have the right to challenge it directly with the credit bureau. But removing long-standing positive tradelines, even accidentally, can actually hurt your score. These accounts contribute to your history length, credit mix, and payment record. Before pursuing any removal, monitor all three reports regularly and track when items are set to expire naturally. Dispute only information that’s genuinely incorrect or misleading, not everything you’d simply prefer wasn’t there.
How to actually track your own tradeline timelines
The date that starts the countdown is not always obvious, and it’s a common source of confusion. For a negative account, the clock starts from the original delinquency date. That’s the date the account first became late and was never brought current again, not the date the creditor charged it off, sold it to a collector, or a new agency reported it. A debt collector picking up an old account does not reset that seven-year window, no matter how the new tradeline is dated on your report.
To find your own timeline, pull your full report from all three bureaus. Look for the “date of first delinquency” or similar field on each negative item — it’s usually listed separately from the account open date and the date reported. Note it down, add seven years, and you have a realistic removal date to work from. For closed positive accounts, the relevant date is simply the closure date, plus ten years.
When a tradeline reappears after being removed
Occasionally, an item that was successfully disputed and removed shows back up later. Under the FCRA, a furnisher can only reinsert previously deleted information under two conditions. It must certify the information is accurate, and it must notify you of the reinsertion within five business days. If a removed item reappears without that notice, that’s worth disputing again and, if necessary, raising with the CFPB.
Your Rights Regarding Tradelines
Two federal laws protect you here. The Fair Credit Reporting Act (FCRA) ensures the accuracy, fairness, and privacy of your credit report information. It gives you the right to dispute inaccurate tradelines, request corrections when errors are verified, and access your report for free once a year from each bureau. The Fair Debt Collection Practices Act (FDCPA) regulates how debt collectors can behave. It prohibits harassment, false claims, or unauthorized reporting to the bureaus.
These laws also restrict what any legitimate credit repair company can do — including one you might hire in Florida. A reputable provider cannot charge in advance under the federal Credit Repair Organizations Act. It can only use legal dispute methods and cannot make false guarantees. If a company promises to “delete all negative items fast,” treat that as a red flag rather than reassurance. Negative tradelines only come off early if they’re actually inaccurate or unverifiable, not simply unwanted. Our guide on how to avoid credit repair scams in Florida covers more of these warning signs, and our guide to Florida credit repair laws explains the specific state and federal protections that apply.
Understand Your Tradelines Before You Act
Knowing how long tradelines stay on your credit helps you manage expectations, prioritize which accounts to address first, and avoid disputing information that will fall off naturally anyway. If you’re not sure where to start, Credit Repair of Florida can help you review your report and build a realistic plan. We do not guarantee deletions or a specific score increase — no legitimate company can — but we can help you understand exactly what’s on your report and why it’s there. If you’re comparing options, our guide to comparing credit repair companies in Florida is a good place to start.
How long do tradelines stay on your credit report?
Positive closed tradelines usually remain for 10 years. Negative tradelines like collections or charge-offs typically stay for 7 years from the original delinquency date.
Do open accounts ever fall off your report?
No, not while they stay open and the lender keeps reporting them. An account only starts its removal countdown once it closes — either paid off, or after negative activity like a charge-off.
How long does bankruptcy stay on my credit report?
Chapter 7 bankruptcy can remain for up to 10 years from the filing date. Chapter 13 typically remains for 7 years.
What’s the difference between installment and revolving tradelines?
Installment tradelines include loans with fixed payments, like car or student loans. Revolving tradelines include credit cards with variable balances you can borrow against repeatedly.
Disputes and Removal
Can tradelines be removed from my credit report early?
Yes, if a tradeline has errors or violates reporting rules, you can dispute it directly through the credit bureaus or with the help of a credit repair service. You cannot remove accurate, verifiable information simply because it’s unwanted.
Can removing a tradeline ever hurt my score?
Yes — removing a long-standing positive tradeline, even by accident, can shorten your credit history length and hurt your credit mix, which may lower your score. Always confirm what you’re disputing before requesting removal.
Is it worth disputing a negative tradeline that’s about to age off anyway?
Generally no. Check the delinquency date first. If the 7-year window is nearly up, the item will fall off on its own — your time is better spent on tradelines that are genuinely inaccurate or have years left on the clock.
Can a credit repair company remove any negative tradeline I want?
No, and be wary of anyone who claims otherwise. A legitimate credit repair company can only dispute information that’s inaccurate, incomplete, or unverifiable — accurate negative history stays on your report for its full reporting period regardless of who requests its removal.
This article is provided for general educational purposes and is not legal, tax, or financial advice. Laws and reporting practices may change, and their application depends on the facts. Consult a qualified attorney for advice about a specific situation.